Aspire Account Center
by Atlanticus Services
3.3
- Safety
- 100% Safe
- Category
- Finance
- Ratings
- 3.3
- Price
- Free
- Download
- 500.00K
This app is secure, reliable, free to install, and offers fast downloads without any risks or malware.
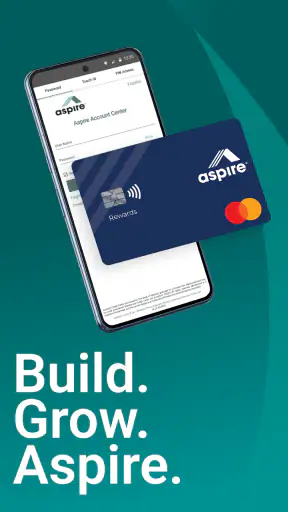
Screenshots
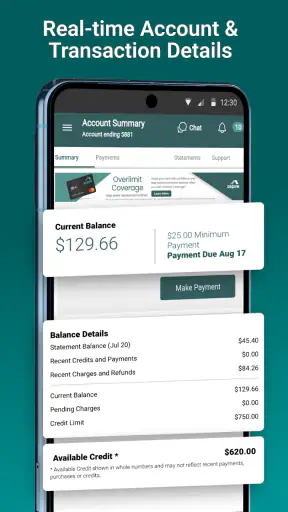
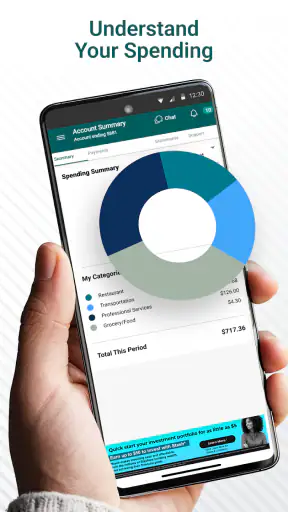
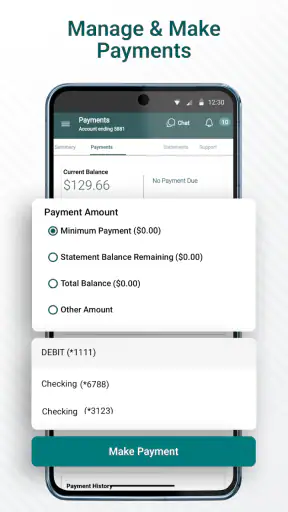
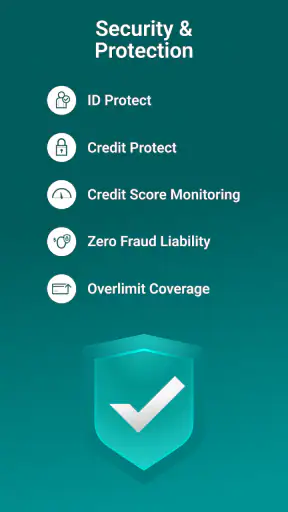
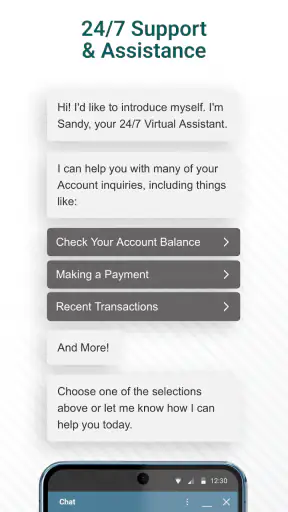
 Analysis by Getfullapps
Managing a credit card from a phone sounds simple, but the practical question is whether the app helps you stay organized without blurring who is actually responsible for the account. I spent time looking at Aspire Account Center from that angle: not just as a finance app for one cardholder, but as something that might be opened on a shared household device, checked during errands, or used while two people coordinate payments and spending.
My overall impression is that it is most useful as a focused account-management tool rather than a complete household-finance system. It puts the Aspire card relationship in one mobile place, which is convenient when you want to check the account without reaching for a browser. At the same time, that narrow purpose matters. It should not be treated like a shared budgeting board, a family expense tracker, or a replacement for clear agreements about who may view or manage financial information.
How it fits into everyday household use
A realistic example is a couple preparing for a busy week. One person is at the supermarket and wants to confirm available card information before paying, while the other is at home reviewing the household bills. A dedicated card-center app can make that coordination quicker than searching through email or opening a general banking website. The benefit is not that it manages the entire household; the benefit is that it gives the cardholder a direct place to handle the Aspire account.
I would be comfortable recommending it for a person who regularly checks one Aspire credit card from a phone. I would be more cautious if the intention is to let several people use the same signed-in device. Financial apps are different from shared shopping or calendar apps: an open session can expose sensitive account details, and convenience should not override account boundaries.
That distinction is especially important in a household where one person owns the account and another simply helps with errands. A partner, older child, roommate, or caregiver may need information for a specific task, but that does not automatically mean they should have unrestricted access. My practical advice is to keep the app tied to the responsible account holder’s device whenever possible and to avoid treating a shared tablet as a neutral place for private financial access.
The app is free to install, which removes an obvious barrier for someone who already uses an Aspire card. It is listed for Everyone, but that age label should not be confused with independent financial suitability. A general audience rating describes the app’s content, not whether a younger household member should be given access to an adult credit account.
What the app is actually good at
The central job is straightforward: manage an Aspire credit card from a mobile device. I see value in that focused approach because it avoids the clutter of a broad money-management platform. If your main need is to stay connected to this particular card, a dedicated center can be easier to remember and quicker to open than a general finance app containing unrelated accounts.
Articles to Explore Next
Uber Eats Makes Dinner Easier to Manage, but the Fees Add Up
Google Photos Turns a Camera Roll Into a Library You Can Find Your Way Through
Canva on Mobile: Adopt It for Quick Visuals, Test It for Demanding Work
Google Drive Keeps Work Moving Until It Doesn’t
Switching to Weather - By Xiaomi Means Relearning Your Forecast Routine
Ludo King and the Social Life of a Lucky Six
That focus also gives the app a clear place in a household routine. The account holder can use it before making a larger purchase, during a payment check, or when reviewing the card as part of a weekly money conversation. The other person can participate in the decision without needing to become the owner of the account or maintain a separate budgeting system inside the app.
One useful habit is to separate “checking the account” from “deciding the household budget.” I would use Aspire Account Center for the first task and a shared note, spreadsheet, or budgeting application for the second. That division prevents a common mistake: assuming that access to card information automatically provides a complete picture of household cash flow, savings, bills, and other cards.
Another practical insight is to use it as a confirmation step rather than a source of last-minute surprises. Before leaving for a purchase, the cardholder can check the account and then tell the other household member what has been confirmed. That small routine is more reliable than passing a phone around at the checkout counter, where a notification, open session, or accidental tap could create unnecessary exposure.
Setup should establish boundaries before convenience
When I set up any finance app, I think about ownership before features. The first question is not “Who might find this useful?” but “Whose account is this, and who should be able to open it?” With this app, that distinction is particularly important because the developer is Atlanticus Services and the app is designed around Aspire card management, not around a general family profile.
I would begin on the primary cardholder’s personal phone, use a device protected by its own passcode or biometric lock, and avoid saving access details where another person can casually retrieve them. I would also check the phone’s notification behavior. Even when the app itself is locked, visible financial alerts on a lock screen can reveal more than intended to someone sharing the device or sitting nearby.
For a household device, I would think carefully before signing in at all. A tablet in a kitchen or living room may feel convenient, but it is also more likely to be left unlocked, handed to guests, or used by children. The safer arrangement is usually one private device for the account holder, with verbal coordination or a separate shared planning tool for everyone else.
This is one of the app’s important trade-offs. A dedicated mobile center can make access faster, but faster access also means the account may be opened more casually. I would not install it on a phone that regularly changes hands unless the owner is willing to maintain strong device security and sign out or lock the device consistently.
For someone helping an older relative, the best setup may be guided use rather than permanent shared access. The account holder can open the app while the helper assists with navigation, then close it afterward. That approach preserves a clearer boundary than storing the account on the helper’s phone simply because the helper is more comfortable with mobile technology.
Coordinating purchases without turning the app into a family dashboard
Household coordination works best when each person knows what the app can and cannot represent. Aspire Account Center can serve as the card-specific reference point, but it does not replace a conversation about spending limits, due dates, reimbursements, or which purchases belong to the household. I would keep those agreements outside the app and use the app only to verify the account details relevant to the moment.
For example, imagine one person asks whether the card is suitable for an appliance purchase. The account holder can check the card center, communicate the result, and record the agreed purchase in the household budget. The other person does not need ongoing access merely to ask that question. This workflow reduces unnecessary sharing while still making the app useful in a joint decision.
A second scenario involves a roommate who occasionally buys shared supplies. I would not treat the app as a way for that roommate to monitor the full card account. Instead, the cardholder could confirm the purchase arrangement and use a shared expense note for the roommate’s portion. That keeps the financial relationship legible: the cardholder manages the card, while both people track the household expense separately.
There is also a useful distinction between an authorized user and an informal helper. If another person has a legitimate role connected to the card, that role should be handled through the account’s official arrangements rather than by casually sharing a login. The app itself should not be used to create an improvised permission system between family members.
My strongest coordination tip is to agree on a simple “ask before using” rule. If the phone belongs to one person and the card belongs to that same person, other household members should not open the app without permission, even if they know the device passcode. That rule sounds obvious, but it prevents the app from becoming an accidental source of conflict when a shared device is involved.
Age, trust, and the meaning of an Everyone rating
The Everyone content rating makes the app approachable from a store perspective, but I would still treat it as an adult financial tool in a household setting. A child may be able to understand a balance or purchase discussion, yet that does not mean the child should be given access to the account center. Age suitability for app content and trust suitability for financial information are separate decisions.
For teenagers learning about money, I would use the app as a teaching aid only with the cardholder present. Showing how a responsible adult checks an account can be useful, but I would avoid handing over an unlocked phone or allowing independent exploration. The lesson should focus on careful decision-making, not on making private account access feel ordinary.
The same principle applies to guests and temporary caregivers. If somebody needs to help with a purchase, the account holder can perform the account check themselves and share only the information needed for that purchase. This is less convenient than passing over the phone, but it is a healthier long-term boundary.
Trust is not only about whether a person is honest. It is also about mistakes, misunderstandings, and accidental exposure. A shared device can retain an open session, display notifications, or make it unclear who last used the account. Keeping the app on the cardholder’s own protected device reduces those risks without requiring complicated household rules.
Performance expectations and everyday friction
The app has been available since June 25, 2019, and the current version is 4.22.47-6102. It supports Android 6.0 and later, so compatibility should be reasonable for people using an older Android phone, provided the device still meets the wider requirements of the current operating environment. I would still keep the phone updated and install the app only through the normal official store route.
Its audience is substantial, with over 500,000 installs, while the average rating sits at 3.3 from around 2,100 ratings and roughly 967 written reviews. I read that as a sign to keep expectations practical: many people find a dedicated card center useful, but a middling average suggests that the experience may not feel equally smooth for everyone.
In my view, the most likely frustration with a focused finance app is not a lack of ambition but the need to move elsewhere for broader tasks. If you want to compare several bank accounts, build a household budget, track cash spending, or see a complete financial picture, this app is unlikely to be the only tool you need. Its strength is direct access to the Aspire relationship, not breadth.
I would also avoid making it the sole source of a time-sensitive household plan. A mobile account center is convenient, but phones can be offline, shared, misplaced, or unavailable. For an important payment routine, I would keep a separate reminder or calendar entry and use the app as the place to check the relevant account information, not as the only memory aid.
That is a subtle but important trade-off. The app can reduce friction when you already know what you need to check. It is less helpful when you expect it to explain your entire financial situation or coordinate several people automatically. Understanding that boundary will make the experience feel more dependable.
Who should choose it, and who should look elsewhere
I think Aspire Account Center is a sensible choice for an Aspire cardholder who wants a free, mobile way to stay connected to that card. It suits someone who prefers a focused app, checks account information while away from a computer, and is comfortable keeping financial access on a personal device.
It is also useful for a household where one person is clearly responsible for the card and the others simply need occasional coordination. In that arrangement, the app becomes a private control point: the owner checks the account, then communicates the relevant result. That is more secure and less confusing than creating a shared login habit.
I would look for a different option if your main goal is collaborative budgeting. A household with several accounts, shared savings targets, recurring bills, and reimbursement tracking will probably benefit more from a dedicated budgeting service or a carefully maintained shared spreadsheet. Aspire Account Center can sit alongside that system, but it should not be expected to replace it.
I would also skip it as a primary solution if you do not have an Aspire credit card or if you want one app to manage unrelated financial institutions. The narrow focus is helpful for the right user and limiting for everyone else. A general banking app may be a better fit when your priority is a broad overview rather than a direct card-centered experience.
People who regularly share one phone should think twice before installing any private finance tool there. The app’s free price does not remove the privacy trade-off. In that situation, a personal device with a screen lock is more important than the convenience of household access.
My household verdict
After looking at the app through a shared-use lens, I see Aspire Account Center as a practical companion for the individual Aspire cardholder, not as a family finance hub. I like the clarity of having one place for the card, and I think that focus can make routine checks easier. The app is free, broadly accessible on Android, and familiar enough in concept for a person who simply wants mobile account management.
My recommendation comes with a firm boundary: keep the account private, coordinate outside the app, and share only the information needed for a specific household decision. That workflow gives you the convenience of mobile access without pretending that a credit-card center is designed for multiple users or shared financial planning.
The rating of 3.3 means I would not describe it as an automatic recommendation for every cardholder. I would install it when direct Aspire account access is the priority, then judge it by how reliably it fits my own routine. If I needed a complete household picture, collaborative controls, or a unified view of several accounts, I would choose a broader finance tool instead.
My final take: Aspire Account Center is worth considering when you want a focused way to manage an Aspire credit card from your own phone. For a household, its best role is private account access paired with clear communication—not shared credentials, not child access, and not a substitute for a real family budget.
Pros
- Centralizes account settings, billing, and subscription details in one place.
- Makes it easier to review Aspire card and account activity.
- Provides quick access to support and account-management options.
- Helps users keep personal and business account information organized.
- Useful for monitoring available services linked to an Aspire account.
Cons
- Some features may require an eligible Aspire account or specific products.
- The app’s usefulness is limited if you rarely change account settings.
- Account-related actions may involve extra verification steps.
- Information may take time to refresh after recent transactions or changes.
- Users may still need another Aspire app for everyday banking tasks.
FAQs for Aspire Account Center
What is Aspire Account Center used for?
Aspire Account Center is designed to give Aspire customers a central place to manage account-related services, review available information, and access support or administrative tools. Depending on the account type and region, its features may include profile management, billing or subscription details, service controls, notifications, and account security options. The exact tools available can vary by user permissions.
Who can use Aspire Account Center?
Access is generally intended for existing Aspire customers, account holders, or authorized users connected to an Aspire service. You may need valid login credentials, an active account, or an invitation from an administrator before the platform will work correctly. Some functions may be restricted based on your role, organization, subscription, location, or the specific Aspire product associated with your account.
Is Aspire Account Center safe for managing account information?
Aspire Account Center may provide access to personal, account, or service-related information, so users should treat it as a sensitive platform. Download it only from an official source, check the developer details, and avoid sharing passwords or verification codes. Use a strong, unique password and enable any available security features, such as multifactor authentication, to reduce unauthorized access.
What should I do if I cannot log in to Aspire Account Center?
If login fails, first confirm that you are using the correct email address, username, and password, and check whether your internet connection is working. Use the official password-recovery option if one is available, and make sure the application is updated. If your account is locked, inactive, or not recognized, contact Aspire support through an official channel rather than relying on unofficial assistance.
Does Aspire Account Center work on Android and iPhone?
Availability can depend on how Aspire distributes Account Center, since some account-management services are offered as a mobile application while others are accessed through a mobile-friendly website. Before downloading, verify that your device meets the listed operating-system requirements and that the publisher is official. Features may also differ between mobile and web versions, particularly for administrative tools.

Aspire Account Center
This site provides independent information about third-party apps and is not affiliated with, or the owner, developer, or distributor of, any app featured here. App names, logos, and trademarks belong to their respective owners. Developer details are provided for reference; please contact the developer directly via aspireit@atlanticus.com, visit https://www.aspire.com, or review their https://www.aspire.com/website-privacy-security-policy/.